July Market Recap
Summer Holds Steady
July Holds Steady
July came in at 38 homes under contract, essentially on par with last July's 36. Flat is not usually worth writing about. For July on Long Beach Island, it is.
July has historically been the island's quietest month for deal-making. Homes are occupied, showing windows are narrow, and buyers are here to be on vacation rather than to shop. July 2022 produced only 16 contracts. July 2023 produced 21. A July that simply holds level with the year before is a break from that pattern.
It fits the shift we’ve been tracking: more buyers are transacting during the summer months than they used to. A growing share of demand comes from higher-priced renters who are now in a position to purchase. They often use time on the Island to explore available listings—or finally tour the home they’ve been eyeing for the past few months.
Supply kept pace. 33 new listings came to market, so buyers had choices rather than scarcity forcing their hand. None of which undoes a slow spring. The island is still running behind 2025 on the year. July says the summer months are holding their own, not that a recovery has started.
A Look at Sales by Price Range
Seven months in, the price story has sharpened. Break every 2026 contract down by asking price and the pullback sits almost entirely at $3M and under, the brackets that make up the bulk of LBI inventory and exactly where asking prices had gotten most stretched.
| Price Bracket | 2025 YTD | 2026 YTD | Change |
|---|---|---|---|
| Under $1M | 26 | 13 | −50.0% |
| $1M – $2M | 103 | 83 | −19.4% |
| $2M – $3M | 67 | 56 | −16.4% |
| $3M – $4M | 25 | 23 | −8.0% |
| Over $4M | 20 | 27 | +35.0% |
| Total | 241 | 202 | −16.2% |
The sub-$1M segment has been cut in half, the $1M to $2M band is down almost 20%, and the $2M to $3M range is off 16%, a combined 22% decline across everything under $3M. Above $4M the story flips. That tier is up 35% year over year, where scarcity and unique high end product keep motivated buyers engaged.

Closings, Pricing & Days on Market
July recorded 21 closings at a median sale price of $2,295,000, the highest monthly median of the year, and an average of $2,468,000. The range ran from $1,130,000 to $4,150,000, a narrow spread with no bottom end activity at all.
Two numbers are worth pausing on. The close-to-list ratio settled at 96.0%, down from 98.0% in May. Buyers are now securing properties for roughly 4% below asking, a far cry from the 100%+ sale-to-list ratios we saw in 2020 and 2021. This shift is largely the result of sellers trying to “set a new bar” in a market where values have become more clearly defined. With greater leverage, buyers can hold the line rather than feeling compelled to pay above market value.
The second is speed. Median days to contract landed at 46, more than double the 21 and 22 that May and June posted. Read alongside the steady contract count, the picture is clear. The homes selling now came to market earlier in the year, waited, and eventually met the buyer at a realistic number.

Cash vs. Financed by Price Range
Through seven months, 186 homes have closed island-wide, and the cash versus financed split is almost perfectly even at 93 to 91. The price bands are where it sharpens. Financing leads at the lower end, but at the top, cash takes over decisively. Buyers above $4M closed 15 in cash to just 5 financed. The higher up the market you go, the more deals get done without a lender.
What's Sitting & What It Means
Active inventory shows exactly where patience is required. The average asking price across active listings is $2,997,000 at roughly $1,222 per square foot, meaningfully above what is actually closing, which ran near $2.47M and about $1,087 per square foot in July.
Active listings are averaging 108 days on market with a median of 72, reflecting both the aspirational pricing common at the top of the range and the reality that higher priced homes take longer to find their buyer.
Of the 126 homes currently active, 87 are priced at $2M and above. That is 69% of inventory sitting in the brackets where buyers have been most cautious, with only 5 active listings under $1M on the entire island. Deep upper tier selection, a thin entry level, and a buyer pool being deliberate about what it will pay. That is the tension of the second half.

For Buyers
That 4% gap between ask and close is real leverage, and it is widest on homes that have been listed since spring. With inventory averaging 108 days on market, patience is being rewarded rather than punished. Come pre-approved and specific about what you want.
For Sellers
The buyers are still here. They are not paying for optimism. Homes priced correctly out of the gate are moving, while homes that come out high sit for months and still give up roughly 4% at the table. Getting the number right the first time is worth more than any adjustment made later.
August Outlook

Buyer Market Outlook
August is the hardest month of the year to get inside an LBI home, and the best month of the year to find a motivated seller. Those two things are related, and understanding why is most of what a buyer needs to know right now.
Access is at its tightest, though only for the first half of the month. Occupancy peaks across the first two weeks of August. Summer renters are in, owners are using their places, and showing windows come down to the gaps between Saturday turnovers. Expect to wait several days for a slot rather than booking same day. This is the single biggest reason casual buyers step away.
From roughly mid month it slowly tapers off. Kids head back to school, families wrap up their weeks, and weekly rentals begin to thin out. You may see a few more open houses come on market as that happens, though the shift is gradual rather than dramatic.
Post Labor Day is when it really opens up. Expect a wave of readily available inventory as rental calendars empty out and owners hand their homes back to the market, showable on short notice for the first time since June. That is the front edge of the fall buying season. It is also when the rest of the buyer pool comes back.
Which is the argument for using August well. Treat this month as a jump start on the fall season. Get financing squared away, tour what you can, and have your shortlist and your priorities settled before Labor Day. Buyers who do that are ready to move the week inventory frees up. Buyers who wait for the wave are starting from the beginning alongside everyone else.
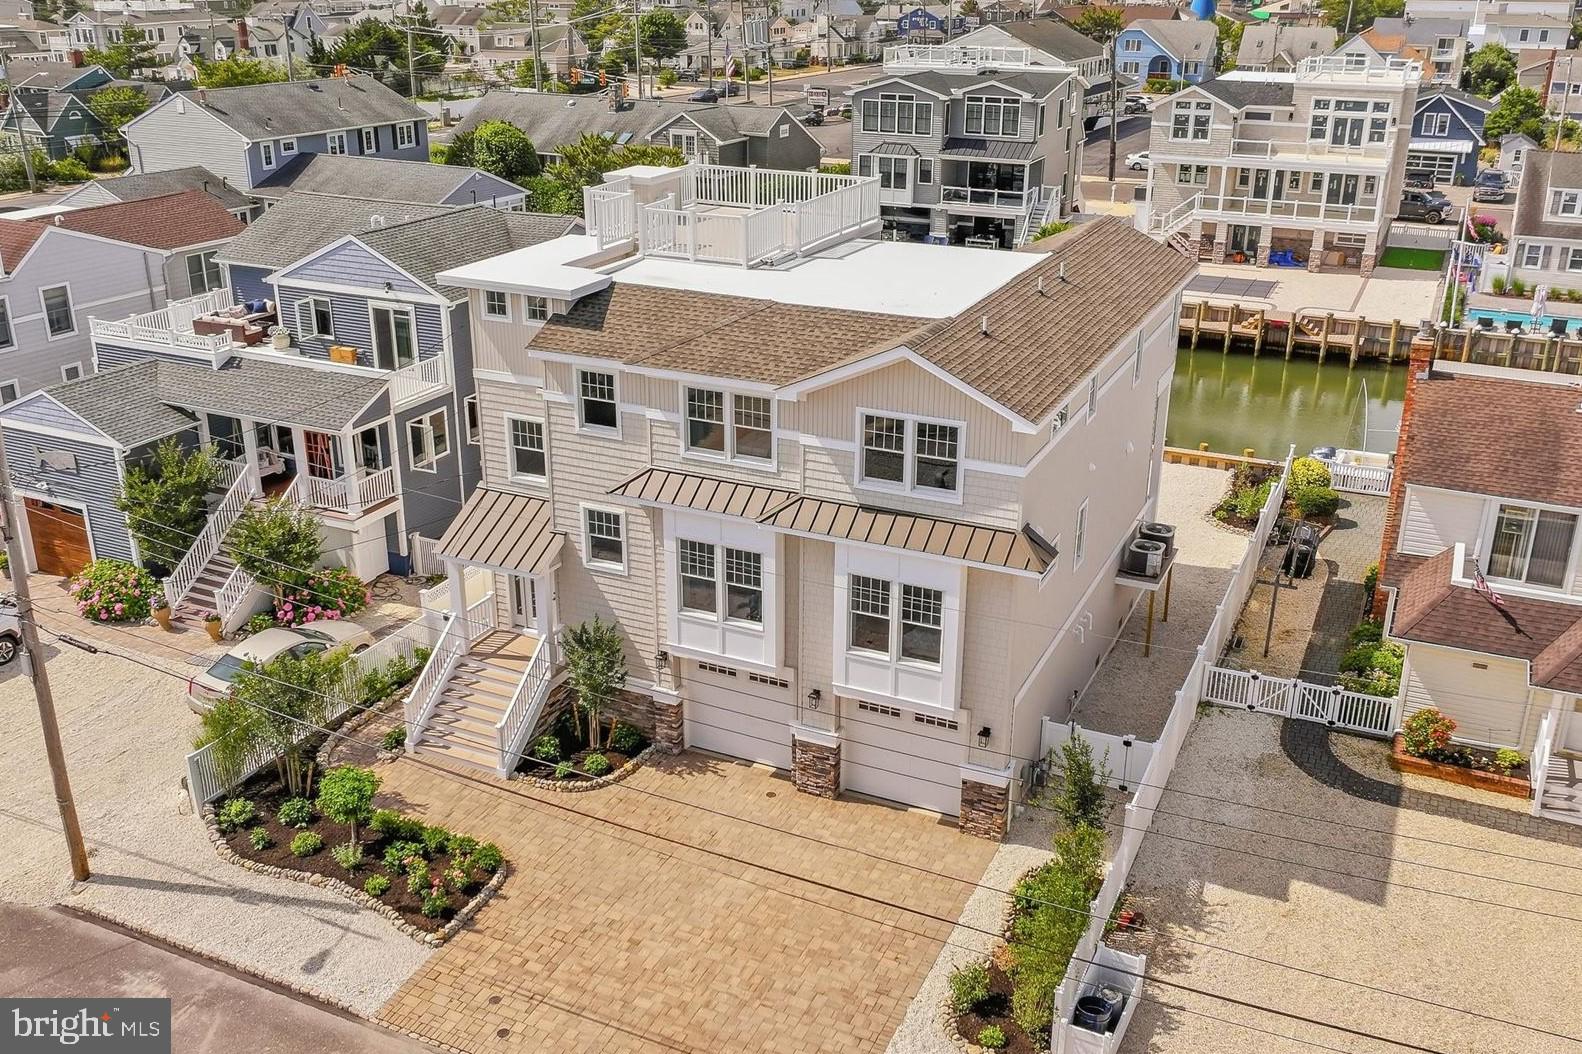
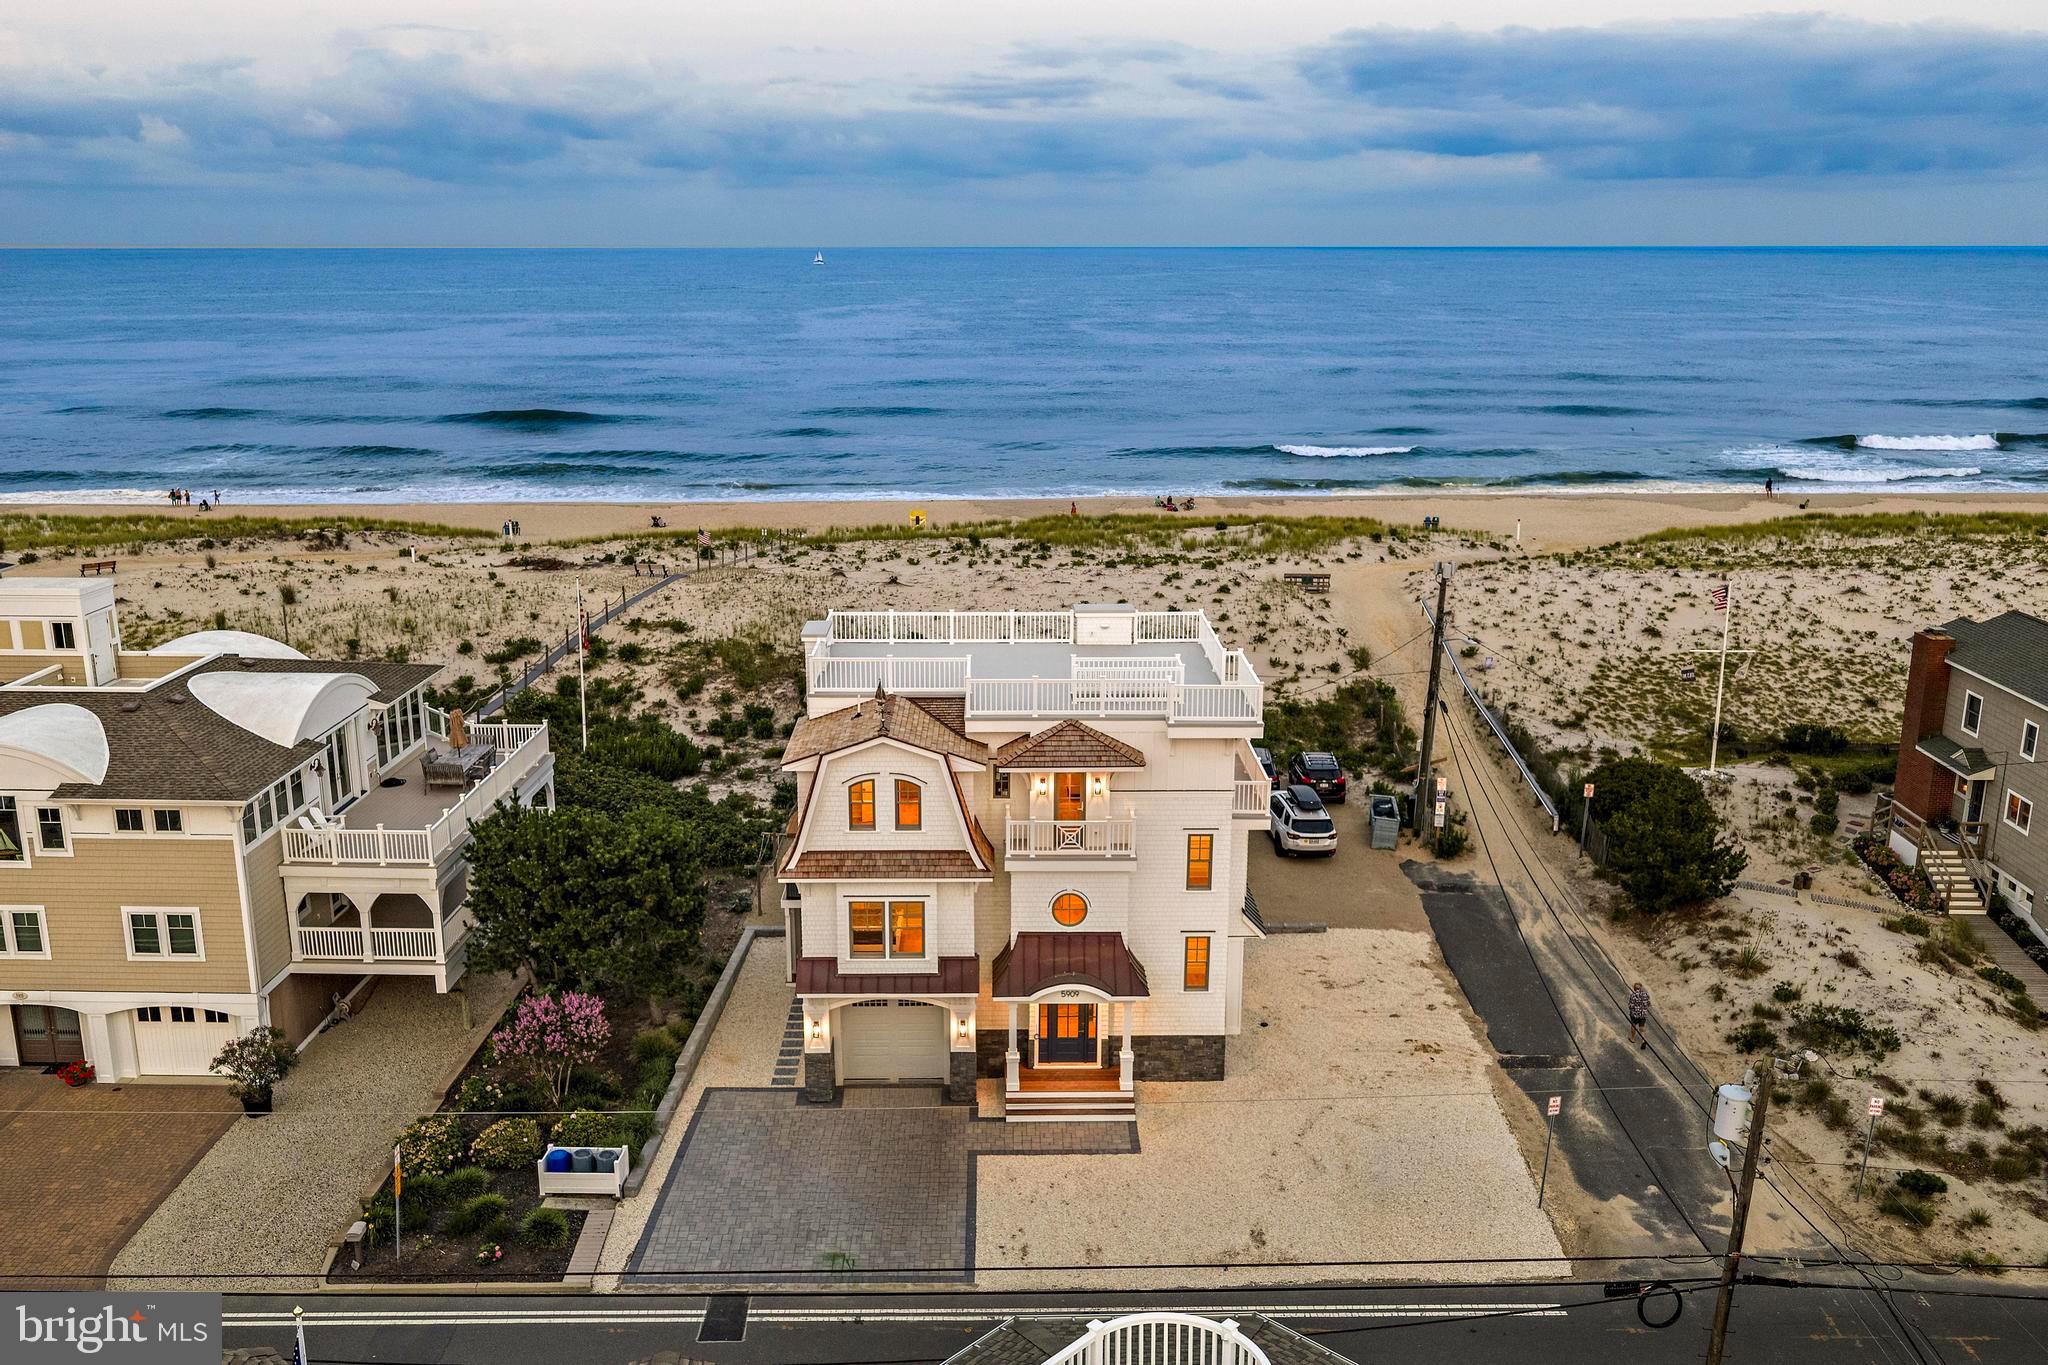
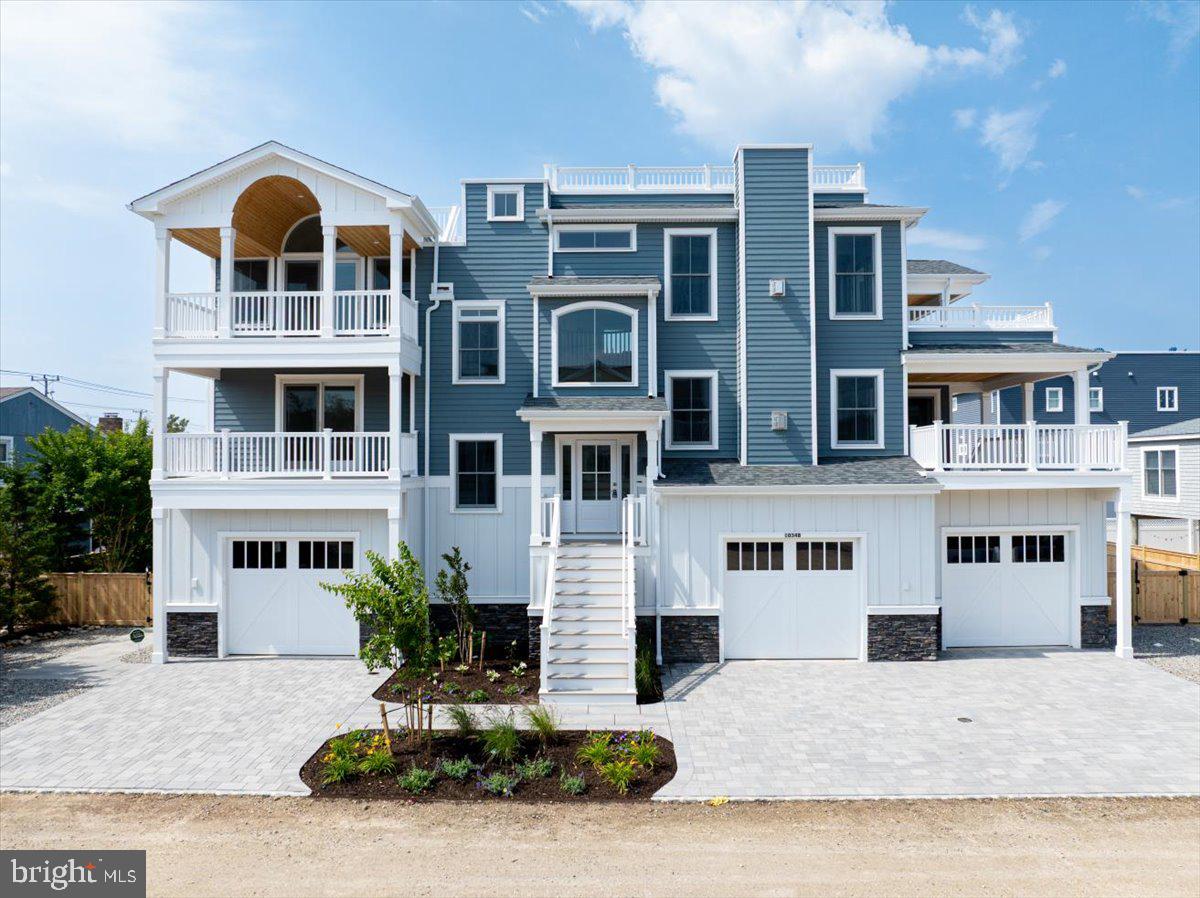
There is one exception, and it is a big one. Open houses have not disappeared in August, but they have concentrated almost entirely on new construction. Of the 126 homes active on the island, 43 are new builds, and those are the only listings with no occupancy to work around. No renters, no owners in residence, no waiting on a Saturday turnover. If you are driving the island on a weekend and seeing signs out, that is most of what you are seeing.
What You Can Actually Walk Into
126 Active Listings · Long Beach Island
Be careful what you conclude from that. A buyer shopping between $1.5 million and $2 million who spends August touring open houses may find almost nothing within their range, and walk away believing the Island has priced them out. It hasn’t. Some of the best value on LBI right now can be found among resale homes that have been listed since spring, very few of which are hosting open houses. Reach out to us to schedule your private showing at these properties.
Seller motivation is also at its highest point since spring. The listings still sitting in August are the ones that came to market in March, April, and May and have now watched an entire selling season pass. Active listings are averaging 108 days on market, up from 99 in May. Once Labor Day comes and goes, the practical choice for those owners is to reprice, relist in the fall, or carry the home through another off season. Many would rather secure a buyer next month than wait around for a wave of new fall listings to hit the market.
That combination is unusual. There is still real selection, but far fewer buyers working through it, and the sellers who remain have a reason to negotiate that they did not have in May. A buyer who is pre-approved, clear on what they want, and willing to plan around occupied homes is in a stronger position in August than at almost any other point in the calendar.
Timing matters too. A contract signed in August generally closes in late September or October, giving a new owner the full off season to handle any work and be ready for next summer. Wait until late in the fall season and the timeline condenses quickly, often meaning a post New Year close.
The takeaway: August’s access hurdles thin the buyer pool just as seller patience begins to wear thin. If you are organized and ready to move, this can be one of the year’s better negotiating windows, and your best opportunity to get ahead of the fall season before more buyers return to the market. Do not let the open-house schedule define your search. We are happy to arrange showings of both vacant properties and coordinate access around the schedules of occupied homes. We also have a direct pulse on which properties have motivated sellers who are ready to negotiate.
Seller Market Outlook
If you assume summer is the off-season for selling on LBI, the numbers say otherwise, and August is the proof. Looking at the five-year average for every month on the calendar, August is the strongest contract month of the summer and one of the strongest of the entire year, well above the roughly 37 contracts an average LBI month produces.
It also sits at the front of the busiest stretch of the year's back half. August into September is the strongest back to back run on the calendar after the winter window, which makes the next eight weeks the most important selling period between now and next spring.
Average LBI Contracts by Month
5-Year Average · 2021–2025 · Excludes Land Sales
The reason is the mix of buyers August produces. The market benefits from both planned buyers and spontaneous buyers, those who came to the Island for a vacation, not to shop for a home, but decided while here that they want to own. Peak visitor volume creates peak spontaneous demand, while also giving buyers who have been searching for some time the convenience of being on the Island for a week, or perhaps an entire month, and the opportunity to explore available homes.
It is the same force behind the "new LBI buyer" we have been tracking, and a growing share of it is new wealth discovering the island for the first time. The clearest evidence is at the top of the market. $4M+ contracts have multiplied roughly five fold since 2019, from 5 that year to 25 in 2025, and 2026 has already passed that with 27 luxury contracts through early August and five months still to run. Much of that growth is new construction, and the market is absorbing it rather than leaving it to sit.

That buyer also tends to pay differently. Of the 20 homes above $4M that have closed this year, 15 were all cash, a 75% share. At the top of the market, financing is increasingly beside the point, which removes appraisal and lender risk from those transactions and generally shortens the path to the table.
If you are selling a resale home, the makeup of current inventory is quietly in your favor. New construction accounts for 43 of the 126 active listings and is asking an average of $3.73M against $2.62M for everything else. A well presented resale priced in the middle of the market has considerably less direct competition than the raw inventory count suggests, because a third of that count is playing in a different price bracket entirely.
August open houses tend to draw well for the same reason the month produces contracts. There are more people on the island than at any other time, and more of them are first timers who did not arrive planning to buy. Cloudy and rainy days are often the strongest of all. When the beach is off the table, that foot traffic has to go somewhere. Right now nearly all of that traffic is funneling into new construction, simply because those are the homes that can open their doors. If your home sits vacant between renters, even for a single weekend, an August open house puts you in front of an audience that does not exist in February and that your occupied competition cannot reach.
None of this changes the one constant: pricing remains the deciding factor. Of the 38 homes that went under contract in July, only 6 did it within two weeks of listing, while 11 had been sitting on the market more than 90 days before a buyer came. The fast ones were priced right out of the gate. The slow ones eventually met the market. August brings the traffic. Accurate pricing is what converts it into an offer.
A practical note on timing. Because September is the single busiest contract month of the second half, the sellers who benefit most from it are the ones already listed and photographed before it arrives. If a fall sale is the goal, August is the month to prepare, not the month to wait out.
The practical takeaway for sellers: August brings out both the planned buyers who are determined not to miss another summer on LBI and the spontaneous buyers looking to cure their post-vacation blues with a home of their own on the Island. Together, they create the strongest eight-week selling stretch on the calendar before spring. For anyone considering a sale in 2026, this is a legitimate selling window, not an off-season. We are happy to review what your home is worth in today’s market and what a realistic selling timeline would look like.






Introducing our Investment Analysis!
Provided to all of our clients, our analysis delivers projected year-over-year ROI, long-term investment projections, rental income estimates, closing costs, and more - all dynamically tailored to your situation.

The Guarino Team
The Island's Fastest-Growing Real Estate Team

We're not just here to open doors — we're here to make sure you walk through the right one.
We don't just know the Long Beach Island market. We live it, invest in it, and study it every single day.
From accurate pricing guidance and rental ROI projections to strategic offer structures that win in competitive situations, we help buyers approach the market with clarity and confidence.
With deep local roots, modern valuation technology, and a relentless work ethic, we're redefining what a real estate advisor should be.
NJ 4-Foot Flood Rule — What It Means for LBI